
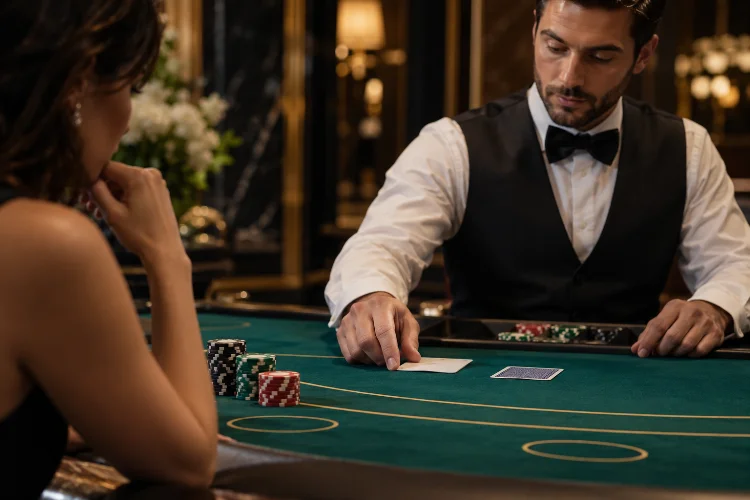
Blackjack can feel simple until the dealer shows an Ace and suddenly asks, “Insurance?” For new players, the offer sounds reassuring, almost like a way to protect a strong hand from bad luck. In reality, blackjack insurance is a separate wager with its own odds and payout.
So, What Is Blackjack Insurance? It is an optional side bet that the dealer’s hidden card is worth 10, completing a natural blackjack. Once you understand that distinction, deciding whether to take insurance becomes more about probability than emotion.
How Blackjack Insurance Works
Insurance is normally offered when the dealer’s visible card is an Ace. A player can make an additional wager, usually up to half the value of the original blackjack bet. If the dealer’s hidden card is a 10, Jack, Queen, or King, the insurance wager wins and normally pays 2:1.
For example, imagine your original bet is $20. You could place up to $10 on insurance. If the dealer has blackjack, that $10 insurance wager generates $20 in profit.
The important detail is that insurance is a seperate bet. It is settled independently from what eventually happens to your normal blackjack hand.
Why Is It Called Insurance?
The name makes the wager sound like protection. If you have $20 on the main hand and the dealer has blackjack, a $10 insurance bet paying 2:1 produces $20 in profit, potentially offsetting the loss on your original wager.
However, you are not really protecting your cards. You are simply betting that the dealer’s hidden card has a value of 10.
That distinction matters. Whether your hand totals 12, 18, or 20 does not automatically improve the insurance bet. The important factor is the probabilty of a 10-value card being underneath the dealer’s Ace.
What Does Blackjack Insurance Pay?
The standard insurance payout is generally 2:1. A $5 wager therefore earns $10 in profit when successful, while a $20 insurance bet would earn $40.
This payout also tells us the break-even probability.
If you risk $1 and receive $2 in profit when you win, the winning event needs to occur one-third of the time for the wager to break even over the long run.
In other words, the dealer must have a 10-value hole card more than approximately 33.33% of the time before insurance becomes mathematically attractive.
That simple calculaton explains much of the strategy behind the decision.
The Math Behind Blackjack Insurance
Consider a simplified single-deck game where the only known card is the dealer’s Ace. A standard deck contains 16 cards worth 10: four 10s, four Jacks, four Queens, and four Kings.
After removing one Ace, 51 cards remain. There are still 16 possible 10-value cards, giving a probability of 16/51, or roughly 31.37%.
That is below the 33.33% break-even point.
BlackjackInfo calculates an insurance house edge of about 5.88% in this simplified single-deck example. Its six-deck example produces an edge of around 7.40% when no additional visible-card information is considered.
This is why ordinary basic strategy generally recommends declining insurance.
What About Even Money?
Things become more interesting when you already have blackjack and the dealer shows an Ace. Some casinos may offer “even money,” allowing you to accept a guaranteed 1:1 profit instead of waiting to see the dealer’s hidden card.
On a traditional table where blackjack pays 3:2, even money is closely connected to insurance. If the dealer also has blackjack, your hand would normally push. If the dealer does not, rejecting even money allows you to recieve the larger 3:2 blackjack payout.
A guaranteed payout can feel safer, but safety and expected value are different ideas. Under normal basic-strategy conditions, players are generally advised to decline even money.
Can Taking Insurance Ever Make Sense?
Yes, but this is where blackjack becomes more advanced.
Insurance can become profitable if the undealt cards contain an unusually large concentration of 10-value cards. Card counters attempt to identify exactly this type of situation.
If enough low cards have already left the shoe, the proportion of remaining 10s may rise above the one-third threshold needed for a 2:1 insurance payout to become attractive.
That does not mean players should rely on intuition. Seeing two or three small cards does not prove the shoe is favorable. Professional card-counting methods track card composition systematically.
For someone playing basic strategy without counting cards, the practical approach is much simpler: insurance is normally a bet to skip.
Smart Tips Before Playing
Always check the blackjack rules before sitting down. Look at the normal blackjack payout, number of decks, dealer rules, and any restrictions on doubling or splitting.
More importantly, do not let a strong hand pressure you into buying insurance. A total of 20 may feel too valuable to “leave unprotected,” but the side bet is still based on the dealer’s hole card.
Insurance also increases the money exposed during a single round. Players working with a limited bankroll should account for that extra volatility rather than treating the wager as free protection.
Blackjack insurance is simply a side bet that the dealer has a 10-value card behind an Ace. Although its 2:1 payout sounds appealing, normal card distribution usually gives the casino an advantage.
Learn the basic strategy, understand the odds, compare table rules, and only consider insurance if you genuinely understand how the remaining card composition changes the math.
